
Investment Property Buying Guide: Everything You Need to Know
Buying property to rent out or resell is a business decision, and it rewards buyers who plan before they sign. This investment property buying guide covers the whole process: setting a realistic budget that includes tax, financing the purchase (including with equity), choosing a strategy, judging a unit on its numbers, and closing safely. You’ll also find a checklist, practical tips, and an honest look at the risks. Examples use Egyptian pounds and reflect a market where off-plan units and developer payment plans are common.
Key Takeaways
- An investment property earns money through rent, rising value, or both.
- Budget for the deposit, maintenance, finishing, fees, taxes, and empty months on top of the price.
- Judge every unit on net yield and cash flow after tax, using cautious assumptions. If a deal only works when everything goes right, walk away.
- Off-plan payment plans lower the entry cost, but rent only starts after handover.
- Work through this investment property buying guide in order: budget, financing, strategy, research, numbers, signing.
What Is an Investment Property?
An investment property is real estate you buy to earn a financial return rather than to live in. The return comes from rent, a rise in value, or both.
| Return type | How you earn it | What drives it |
| Rental income | Monthly or annual rent | Tenant demand, location, finishing |
| Capital growth | A higher price when you sell | Area development, supply, inflation |
A rental property buying guide focuses on income, while growth investors care more about resale value. Either way, judge a unit by what it can earn rather than whether you’d enjoy living in it. An investment property buying guide that leads with finishes and views instead of yield reads more like a sales brochure.
Investment Property Checklist – What to Know Before You Buy
What to know before buying an investment property falls into three areas: how much you can spend, how you’ll pay, and what you want the property to do. Run through this investment property checklist before visiting any sales center:
- A total budget covering every cost, including tax
- A confirmed financing route and a written payment schedule
- A clear strategy: income, growth, or a mix
- Research on local demand, supply, and infrastructure
- Tested numbers: net yield, cash flow, and a worst case
- A lawyer’s review of the developer and contract
Set Your Budget and Deposit
Your budget is the total cash you can commit without straining your finances, and it’s always larger than the unit’s price. Sales pitches lead with the down payment, but a useful investment property buying guide works from the upfront total, which is what you actually need in the bank.
| Cost type | What it includes |
| Upfront | Down payment, maintenance deposit, legal and registration fees, finishing, furnishing |
| Ongoing | Installments, service charges, repairs, management fees, property and rental income taxes |
| Reserve | Cash for handover delays, empty months, or a drop in income |
Keep a reserve covering at least six months of installments and running costs. It decides whether a late handover is an inconvenience or a forced sale.
Account for Property Taxes
Tax affects both your budget and your real return. Egyptian investors typically deal with three:
- An annual real estate tax on built property
- Income tax on rental earnings
- Tax on the sale when you dispose of the property
Rates and exemptions change, so confirm current rules with an accountant or the Egyptian Tax Authority. Any investment property buying guide that skips tax overstates returns, so carry these costs into the yield figures in Step 4.
Understand Your Financing Options (How to Buy an Investment Property With Equity)
Buyers in Egypt usually choose one of four routes.
| Option | Advantage | Drawback |
| Cash | Largest discounts, no debt | Ties up capital |
| Developer installment plan | Low down payment, long terms | Costs more than cash; off-plan units earn nothing until handover |
| Bank or mortgage finance company | Funds completed units | Usually needs registered title and proof of income |
| Equity release | Funds a deposit without selling | Your home secures the loan |
The Central Bank of Egypt regulates banks, and the Financial Regulatory Authority (FRA) supervises mortgage finance companies. An investment property buying guide written for mortgage-driven markets assumes a bank lends most of the price. For off-plan units in Egypt, developer installment plans usually fill that role, which lowers the entry cost but delays income.
How to Calculate Usable Equity
Learning how to buy an investment property with equity starts with usable equity: the share of your home’s value a lender will lend against, minus what you still owe.
- Value your home, say at EGP 8 million.
- Apply the lender’s limit. At an illustrative 60%, that’s EGP 4.8 million.
- Subtract your EGP 2 million debt, leaving EGP 2.8 million of usable equity.
Borrowing against your home ties both properties to the same market, so confirm eligibility and repayments with your bank first.
Define Your Investment Strategy
Strategy is where a generic investment property buying guide can mislead you, because advice written for buy-and-hold landlords doesn’t fit someone buying off-plan to resell.
| Strategy | How it earns | Trade-off |
| Long-term rental | Annual leases, steady rent | Less work; rent fixed per lease |
| Furnished or short-term rental | Higher potential monthly income | More turnover; building rules may restrict it |
| Off-plan capital growth | Buy at launch, sell or rent after completion | Depends on the market and resale terms |
| Hybrid | Growth, then rent after handover | Needs cash for installments until rent starts |
If you need rental income within a year, an off-plan unit won’t provide it, however attractive the payment plan looks.
Step-by-Step: How to Buy an Investment Property
The checklist covers preparation, and the five steps below cover action. Order matters when you follow an investment property buying guide: touring show units before your financing is settled is an easy way to fall for one you can’t afford.
Step 1 – Research the Market
Start with demand. A unit nobody wants to rent is a liability however cheap it is, so find out who rents in the area (young professionals, families, company staff) and what they need. Then:
- Count nearby units due for delivery soon. Heavy supply can hold rents down.
- Map schools, hospitals, main roads, and business hubs within a realistic commute.
- Compare asking rents on portals with what local brokers say similar units actually lease for.
- Check a portal’s area property guide and recent resale listings against developers’ launch prices.
Local evidence beats any generic investment property buying guide at this stage, because demand can differ sharply between neighboring compounds.
Step 2 – Secure Financing
If you’re borrowing, get pre-approval before committing to a unit. With a developer plan, get the full payment schedule in writing, including when the maintenance deposit and other fees fall due.
Next, stress-test the plan. Could you keep paying if handover slipped by a year, or if the unit sat empty for six months after delivery? If not, shop in a lower price range. Late installments often carry penalties, and some developer contracts allow cancellation after missed payments.
Step 3 – Choose the Right Property
Knowing what to look for in an investment property comes down to what a tenant, and later a buyer, will pay for:
- Easy access to work hubs, main roads, and services.
- A size and layout that suit your likely tenant. Oversized units are hard to rent at a price that justifies their cost.
- Amenities tenants notice: security, parking, green space, and storage.
- A clear finishing level and a costed plan to make the unit rentable.
- A developer whose finished projects were delivered on time and are well maintained.
- Clean legal status: land ownership, permits, and title.
Step 4 – Run the Numbers
Rental yield is the figure every investment property buying guide quotes, but the gap between gross and net widens quickly once fees, service charges, vacancy, and tax come off.
| Metric | Formula |
| Gross rental yield | Annual rent ÷ price × 100 |
| Net rental yield | (Annual rent minus costs) ÷ (price plus upfront costs) × 100 |
| Monthly cash flow | Rent minus installment and running costs |
| Total return | Net rent plus capital growth |
Hypothetically, an EGP 5 million unit renting for EGP 300,000 a year yields 6% gross. Take off EGP 60,000 in annual costs and add EGP 500,000 of upfront costs to the price, and net yield falls to about 4.4% (EGP 240,000 ÷ EGP 5.5 million) before tax.
Search for “buying an investment property calculator” to find free tools for a first pass, then build your own spreadsheet that assumes at least one empty month a year.
Step 5 – Close the Deal
No investment property buying guide can fix a bad contract after you’ve signed it, so have an independent real estate lawyer review it first. Check:
- The payment schedule, delivery date, and late-delivery penalties
- Finishing specifications and what happens if they change
- Resale and transfer conditions, including fees
- Maintenance deposit terms and cancellation clauses
For a resale unit, confirm the chain of ownership and that the seller owes nothing to the developer. Ask your lawyer about registering the unit with the Real Estate Publicity Department, since registered title makes resale and mortgage financing easier. Pay by traceable bank transfer and keep every receipt.
Investment Property Buying Tips
These investment property buying tips cover the judgment calls where buyers most often lose money.
- Buy on the numbers, not the show unit. Sales centers exist to sell.
- Visit at rush hour and check the commute, parking, and security as a tenant would.
- Don’t over-finish a rental. Luxury upgrades rarely raise the rent enough to cover their cost.
- Whether it’s a developer brochure, an investment guide pdf, or an online investment property buying guide like this one, confirm every figure in writing.
- Read the resale clause. Some developers charge transfer fees or restrict resale until a set share of the price is paid.
- Know who would buy the unit from you, and why, before you buy it.
- Hire professional management if you live abroad or own several units.
Applying the Investment Property Buying Guide to Regent’s Square in New Cairo
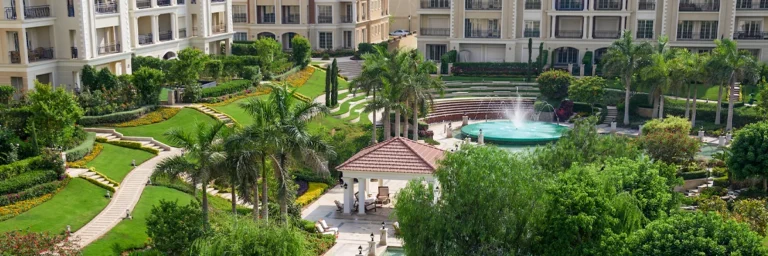
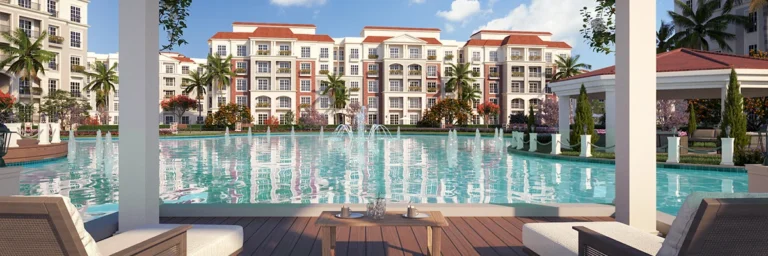
Regent’s Square is a boutique, high-end project by Al Dawlia Developments in the Golden Square area of New Cairo, currently under construction. The developer positions it as its latest masterpiece for buyers who want nature and luxury together, with Victorian-inspired design across apartments, studios, and duplexes.
The site covers 25 acres, with buildings on just 23% of the land and the remaining 77% given to landscaping, lakes, and wide internal roads. Facilities include a commercial strip mall, sustainability features, 24/7 security and surveillance, private storage rooms, and underground parking for every unit, plus optional mechanical parking.
| Unit type | Size range |
| 2 bedrooms | 108 to 136 m² |
| 3 bedrooms | 153 to 228 m² |
| Duplexes | 301 to 344 m² |
Running the Numbers on a Regent’s Square Unit
Running this project through an investment property buying guide starts with its terms: 5% down with the balance over 8 years, a 10% maintenance deposit, and a 40% cash discount. The table applies those percentages to the published average of EGP 96,000 per m² on 108 m², as illustration rather than a unit quote.
| Illustrative item | Arithmetic |
| 108 m² × EGP 96,000 | EGP 10,368,000 |
| 5% down payment | EGP 518,400 |
| 10% maintenance deposit | EGP 1,036,800 |
| After a 40% cash discount | EGP 6,220,800 |
Get the developer’s installment schedule in writing. Before committing:
- Budget early for the maintenance deposit, which exceeds the down payment.
- Rent starts only after handover, so fund installments from other income until then.
- Finishing is listed as 80% basic finishing, so ask what that covers.
- Weigh the cash discount against what that money could earn elsewhere.
Full details are in the Regent’s Square E-brochure.
Is It Smart to Buy an Investment Property? Risks vs Rewards
It is, if you buy on cautious numbers, keep a cash reserve, and can hold for several years. It’s a poor move if you’re counting on a quick price rise or stretching your finances to get in. Your cash position matters more than market timing here, whatever an investment property buying guide or sales agent predicts about prices.
Potential Rewards
- A well-chosen unit brings regular rent that can rise as the area matures.
- Buying early in a developing area can bring real price gains by completion.
- Egyptian buyers have long used property to protect savings from high inflation and a weaker pound.
- Installment plans let you control a large asset with a small upfront share of its price.
- You can add value directly through finishing and good management, which shares and bank certificates don’t allow.
Risks to Consider
- Selling can take months, and resale units compete with new launches offering long payment plans.
Delivery delays push back rent while installments continue. - Leverage magnifies losses as well as gains. Installments stay due whether or not the unit earns, a point an optimistic investment property buying guide rarely dwells on.
- Empty months and difficult tenants cut into your yield.
- A cluster of handovers nearby can cap rents and resale prices.
- Putting most of your savings into one unit ties you to one market and one developer.
FAQs
Is it smart to buy an investment property?
Yes, for buyers with steady income and savings beyond the deposit, provided the property still makes sense with cautious rent estimates and no price growth for the first few years. It becomes a gamble when the deposit is borrowed, the rent assumption is optimistic, or the plan depends on a quick resale.
How much down payment do you need for an investment property?
Usually 20% or more with a bank, while some developer plans in Egypt start at 5%. Banks tend to ask for a bigger deposit on an investment property than on a home you’ll live in. Regent’s Square in New Cairo, for example, asks for 5% down with the balance over eight years. Maintenance deposits, fees, and finishing add to that upfront cash.
What is a good ROI for an investment property?
A good ROI beats lower-risk alternatives by enough to cover property’s costs, slow resale, and management effort. In Egypt, compare your expected net rental yield plus realistic price growth with current bank certificate rates and inflation. Whatever investment property buying guide you follow, judge total return after tax over your whole holding period rather than the first year alone. If the property only wins under optimistic growth assumptions, the margin is too thin.